 luckpanda
Quick answer
What should a hotel bill show, and how is GST charged on it?
A hotel bill lists the room nights at the tariff actually charged, then food, laundry and other services on separate lines, each with its own GST rate. Since 22 September 2025 a room charged at ₹7,500 or less per night is taxed at 5% without input tax credit, and a dearer room at 18%. The place of supply is the hotel's location, so every guest pays the CGST and SGST of the hotel's state.
- Room up to ₹7,500 per unit per day: 5%, and the hotel cannot opt for 18%. Above ₹7,500: 18%.
- Restaurant food is 5%, or 18% if the hotel is a "specified premises".
- A guest from another state still pays CGST + SGST, never IGST.
- A business guest needs the company's name and GSTIN on the bill, ideally a GSTIN in the hotel's state.
Last reviewed:
On this page
- What a hotel bill is and when it is issued
- How to fill in this hotel bill format
- Example: a three-night business stay
- What goes on a hotel bill, field by field
- GST on hotel rooms, food and services after 22 September 2025
- Why a guest from another state still pays CGST and SGST
- Business travellers and corporate bills
- Advance deposits, cancellations and no-shows
- Small hotels, lodges and homestays
- Mistakes to avoid on a hotel bill
- Hotel bill vs restaurant bill vs travel agent bill
- Key terms
- Questions people ask
What a hotel bill is and when it is issued
A hotel bill is the tax invoice a hotel, lodge, guest house or homestay issues at check-out for everything the guest owes: room nights, meals, laundry, minibar, transport and any other service. During the stay these charges sit on the guest folio, a running account. At check-out the folio is closed and becomes the bill, and the payment is recorded against it.
A GST-registered hotel must issue a tax invoice for the supply. Because one bill mixes supplies taxed at different rates, each charge needs its own line, its own SAC code and its own rate. A bill that lumps "room and food" into one figure cannot show the right tax, and a business guest cannot use it to claim credit.
| Document | What it is | Tax status |
|---|---|---|
| Folio | Running list of charges during the stay | Internal; not a tax document |
| Receipt voucher | Issued when an advance or deposit is received | Required under GST for advances (rule 50) |
| Hotel bill (tax invoice) | Final bill at check-out, every charge with its GST | The tax document the guest keeps |
| Payment receipt | Proof the bill was paid, with mode and reference | Optional; often printed on the bill |
| Refund voucher | Issued when an advance is returned and no stay happens | Required under GST (rule 51) |
How to fill in this hotel bill format
- Enter the hotelAdd the hotel's legal name, address and GSTIN. The state in the GSTIN is the state the tax will be charged in.
- Add the guest or companyFor a business stay, enter the company name, address and GSTIN (its registration in the hotel's state if it has one) and put the guest's name in the name or notes.
- Set the place of supplyKeep the place of supply on the hotel's own state; this example starts that way. Left on automatic, it follows the customer's GSTIN and would charge IGST to a guest from another state.
- Bill the room nightsAdd one line for the room: nights as the quantity, the per-night value as the rate, SAC 996311, and 5% if the value is ₹7,500 or less, otherwise 18%.
- Add food and other servicesAdd restaurant, room service, laundry and spa on separate lines with their own rates. Note check-in and check-out times, the deposit received and the payment mode in the notes.
- Issue itCheck the CGST and SGST split, then sign in to issue: the bill gets the next number in your series, is recorded in your books and is ready for GSTR-1. Downloading the PDF is free, with a small LuckPanda footer; issuing, sending and clean PDFs without our branding need the Sales module.
Example: a three-night business stay
Anand Kulkarni of Deccan Software Services, Pune, stays three nights at Hotel Lakeview Residency in Udaipur at ₹4,800 a night, eats dinner in the hotel restaurant and sends clothes to the laundry. The room is below ₹7,500, so it is taxed at 5%. The hotel has no room priced above ₹7,500, so its restaurant charges 5% too. Laundry is 18%. The hotel is in Rajasthan, so although the guest's company is registered in Maharashtra, the bill carries Rajasthan CGST and SGST.
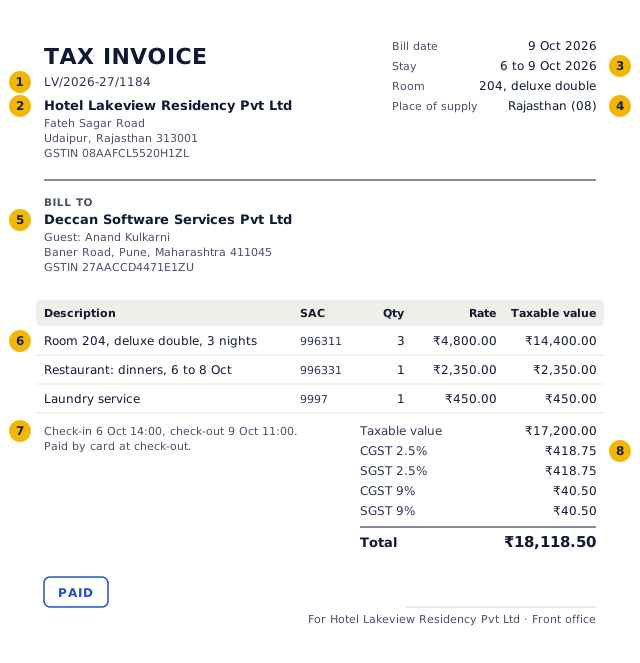
- Bill number: consecutive, at most 16 characters, unique for the financial year.
- Hotel legal name, address and GSTIN.
- Stay dates: check-in and check-out decide the number of nights, and the per-night value decides the room rate.
- Place of supply: the state where the hotel is, whatever the guest's address or GSTIN.
- Guest or company: for a business stay, the company name and GSTIN, plus the guest's name.
- SAC per line: 996311 for rooms, 996331 for restaurant service, the service's own code for the rest.
- Times and payment: check-in and check-out times, advance adjusted and payment mode.
- CGST + SGST at each line's rate: 2.5% + 2.5% on room and food, 9% + 9% on laundry.
The numbers: bill LV/2026-27/1184
| Item | HSN/SAC | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|---|
| Room 204, deluxe double, 3 nights | 996311 | 3 | ₹4,800.00 | ₹14,400.00 | ₹720.00 |
| Restaurant: dinners, 6 to 8 Oct | 996331 | 1 | ₹2,350.00 | ₹2,350.00 | ₹117.50 |
| Laundry service | 9997 | 1 | ₹450.00 | ₹450.00 | ₹81.00 |
| Taxable value | ₹17,200.00 | ||||
| CGST 2.5% | ₹418.75 | ||||
| SGST 2.5% | ₹418.75 | ||||
| CGST 9% | ₹40.50 | ||||
| SGST 9% | ₹40.50 | ||||
| Total | ₹18,118.50 | ||||
The room nights come to ₹14,400 with ₹720 of GST at 5%, and the bill total is ₹18,118.50. The editor above keeps the place of supply on the hotel's own state: once you enter your hotel's GSTIN, it shows CGST and SGST even for this Maharashtra guest. Keep it there on your own bills: left on automatic, the place of supply follows the customer's GSTIN, which is wrong for accommodation.
A dearer room in a specified premises
Aravalli Palace Hotel in Jaipur charges ₹9,200 a night, so its rooms are taxed at 18% with input tax credit, and because it sold rooms above ₹7,500 last financial year it is a specified premises: its restaurant charges 18% too. Spa treatments are "beauty and physical well-being" services, which have been 5% without credit since 22 September 2025, even inside a luxury hotel. The guest's company is in Gujarat; the tax is still Rajasthan CGST and SGST.
Two nights above ₹7,500, with restaurant and spa
| Item | HSN/SAC | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|---|
| Premier room, 2 nights | 996311 | 2 | ₹9,200.00 | ₹18,400.00 | ₹3,312.00 |
| Restaurant (specified premises) | 996331 | 1 | ₹3,600.00 | ₹3,600.00 | ₹648.00 |
| Spa: massage, 60 minutes | 99972 | 1 | ₹2,500.00 | ₹2,500.00 | ₹125.00 |
| Taxable value | ₹24,500.00 | ||||
| CGST 2.5% | ₹62.50 | ||||
| SGST 2.5% | ₹62.50 | ||||
| CGST 9% | ₹1,980.00 | ||||
| SGST 9% | ₹1,980.00 | ||||
| Total | ₹28,585.00 | ||||
The rate is decided per unit per day: a ₹9,200 room is 18% even if the guest stays only one night, and a ₹7,500 room is still 5% because the lower slab includes ₹7,500.
What goes on a hotel bill, field by field
| Field | What to enter | Why |
|---|---|---|
| Title | "Tax invoice" (or "Bill of supply" if the hotel is under composition) | Tells the guest which tax document it is |
| Hotel details | Legal name, address, GSTIN, phone | Rule 46 particulars; the guest's company checks the GSTIN |
| Bill number and date | Next number in the series, e.g. LV/2026-27/1184 | Unique for the year; up to 16 characters |
| Guest | Guest name, and for business stays the company name, address and GSTIN | Needed for the company's input tax credit and reimbursement |
| Stay | Room number and type, check-in and check-out dates and times, nights | Shows the period billed and the per-night value |
| Room charges | Nights x tariff actually charged, SAC 996311, GST rate | The rate depends on the value per unit per day |
| Food and beverages | Restaurant, room service, minibar, by date or itemised | Separate rate from the room unless included in the tariff |
| Other services | Laundry, spa, airport transfer, telephone, each on its own line | Each service has its own SAC and rate |
| Tax | CGST and SGST per rate (UTGST in a union territory) | Never IGST for accommodation in India |
| Place of supply | The hotel's state and code, e.g. Rajasthan (08) | Required on the invoice; explains why the tax is CGST + SGST |
| Advance and balance | Deposit received (receipt voucher number), balance payable | Ties the advance, which was taxed when received, to the bill |
| Payment and signature | Mode, reference, front-office signatory | Proof of payment for reimbursement |
Guests registered under GST should always get their GSTIN on the bill. For an unregistered guest, a hotel bill of ₹50,000 or more must also carry the guest's name and address and the state, as rule 46 requires for large B2C invoices.
GST on hotel rooms, food and services after 22 September 2025
Notification 15/2025-Central Tax (Rate) changed the rates for accommodation from 22 September 2025. The 12% slab for rooms up to ₹7,500 went; those rooms are now 5% without input tax credit. Rooms above ₹7,500 stay at 18%.
| Charge | GST | Input tax credit for the hotel |
|---|---|---|
| Room, value up to and including ₹7,500 per unit per day | 5% (2.5% CGST + 2.5% SGST) | Not allowed; the rate is mandatory |
| Room, value above ₹7,500 per unit per day | 18% (9% + 9%) | Allowed |
| Restaurant, room service, in a hotel that is not a specified premises | 5% | Not allowed |
| Restaurant, room service, banquets with food, in a specified premises | 18% | Allowed |
| Breakfast or meals included in the room tariff | The room's rate, on the whole tariff | As for the room |
| Spa, salon, gym (beauty and physical well-being) | 5% | Not allowed, even in a luxury hotel |
| Laundry and dry cleaning | 18% | Allowed |
| Hall or conference room hired without food | 18% | Allowed |
| Liquor | Not GST; state VAT or excise | Bill it separately |
The ₹7,500 test is on the value actually charged
The threshold is applied to the value of supply of a unit of accommodation per day: the amount the guest actually pays for that room for that night, after discounts and including extra-bed charges. The older "declared tariff" test has been dropped. A room listed at ₹9,000 and sold at ₹6,900 is a 5% room; a ₹7,000 room with a ₹900 extra bed is a ₹7,900 room and goes to 18%. There is no longer any exemption for cheap rooms: rooms below ₹1,000 have been taxable since 18 July 2022.
What makes a hotel a specified premises
The restaurant rate depends on whether the property is a specified premises for the financial year. From 1 April 2025 that means either: in the preceding financial year the hotel supplied any unit of accommodation at a value above ₹7,500 per day; or the hotel declared the property a specified premises, between 1 January and 31 March of the preceding year (or within 15 days of registration for a new registration). A specified premises charges 18% with credit on all its restaurant and catering supplies, including to walk-in diners and to guests in 5% rooms. Every other hotel restaurant charges 5% without credit. A stand-alone restaurant cannot opt into 18%.
Packages: room with breakfast or meals
A tariff that includes breakfast (CP) or all meals (AP) is a composite supply whose principal supply is the room, so the whole tariff takes the room's rate and the threshold is tested on the full tariff. Show it as one line, for example "Deluxe double with breakfast", rather than splitting the breakfast out at a different rate.
Why a guest from another state still pays CGST and SGST
For lodging in a hotel, inn, guest house, homestay, club or campsite, section 12(3) of the IGST Act fixes the place of supply at the location of the property. The guest's home state, the company's GSTIN and where the booking was made do not matter. A hotel in Rajasthan therefore charges Rajasthan CGST and SGST to every guest, including a company registered in Maharashtra. IGST on an Indian hotel bill is an error.
This matters for the business guest. CGST and SGST charged in Rajasthan can generally be used only by a Rajasthan registration. When the bill carries a Maharashtra GSTIN, the guest's GSTR-2B shows the invoice with input tax credit marked not available, because the place of supply is in a different state from the recipient. Some advisers argue the law itself does not deny the credit, but the portal does, and most companies do not claim it.
- What GSTIN should a company give the hotel?
- The GSTIN of its registration in the hotel's state, if it has one (for Deccan Software Services, its Rajasthan GSTIN 08AACCD4471E1ZU rather than its Maharashtra one). If it has no registration there, give the GSTIN anyway: the bill still documents the expense, even if the credit is not usable.
- What if the hotel has issued an IGST bill?
- Ask for it to be corrected with a credit note and a fresh invoice charging CGST and SGST. An IGST bill for accommodation is a wrong tax type, and the hotel's return will not match.
- Does the 5% "without ITC" rate stop the guest claiming credit?
- No. "Without ITC" restricts the hotel's own credit on its inputs. A registered guest can claim the 5% charged on a business stay if the usual conditions are met, including the state point above.
Business travellers and corporate bills
- Room charges on a business trip are eligible input tax credit for the company, subject to the conditions of section 16 and the place-of-supply point above.
- Food and beverages are blocked credit under section 17(5)(b) of the CGST Act, whatever the rate. Companies claim the room and expense the meals.
- Leave travel is blocked too: travel benefits given to employees on vacation, such as a holiday stay under leave travel concession, are not eligible for credit.
- Corporate bills to a company account: when the company pays directly (a "bill to company" reservation), the hotel bills the company with the guest's name in the description or notes. For long stays or group bookings, hotels often issue one bill per guest per stay so each employee's claim is separate.
- E-invoicing: a hotel whose aggregate turnover has exceeded ₹5 crore in any year since 2017-18 must generate an IRN for each bill to a GST-registered company. Bills to individual guests do not need an IRN.
Advance deposits, cancellations and no-shows
For services, GST is due on an advance when it is received, not when the guest arrives. A hotel that takes a deposit issues a receipt voucher showing the amount, the rate and the tax, and pays GST on it for that month. The final bill at check-out shows the full stay, deducts the deposit and collects only the balance; the tax already paid on the deposit is adjusted. If the stay never happens and the deposit is returned, the hotel issues a refund voucher.
Cancellation and no-show charges are consideration for the same supply. CBIC Circular 178/10/2022-GST says cancellation charges for hotel accommodation are taxed at the rate that applies to the accommodation itself. A one-night retention on a cancelled ₹4,800 room is therefore taxed at 5%:
Retention charge on a cancelled booking
| Item | HSN/SAC | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|---|
| Cancellation: 1 night retained, booking LV-88412 | 996311 | 1 | ₹4,800.00 | ₹4,800.00 | ₹240.00 |
| Taxable value | ₹4,800.00 | ||||
| CGST 2.5% | ₹120.00 | ||||
| SGST 2.5% | ₹120.00 | ||||
| Total | ₹5,040.00 | ||||
The hotel keeps ₹5,040 of the deposit, issues this bill for it and refunds the rest with a refund voucher.
Small hotels, lodges and homestays
- Not registered: a hotel below the registration threshold (₹20 lakh of turnover in most states, ₹10 lakh in some special category states) charges no GST and issues a plain bill or cash memo with no tax lines.
- Composition scheme: composition is open to restaurants, not to accommodation, except for small service suppliers under the separate 6% scheme for turnover up to ₹50 lakh. A hotel under that scheme issues a bill of supply, collects no GST and the guest gets no credit.
- Hostels and paying guest accommodation: residential accommodation of up to ₹20,000 per person per month, supplied for at least 90 continuous days, is exempt; that is not hotel accommodation and is billed without GST.
- Lodges and guest houses that are registered follow the same 5% / 18% rule as hotels.
Mistakes to avoid on a hotel bill
- Charging IGST to an out-of-state guest. Accommodation is always taxed where the property is.
- Testing the rate on the published tariff. Use the value actually charged per room per night, including extra beds, after discounts.
- Using 12%. The 12% slab for rooms ended on 21 September 2025.
- Offering 18% with credit on a ₹6,000 room. The 5% rate is mandatory for rooms up to ₹7,500.
- One line for room and food. Unless the food is part of the tariff, it is a separate supply that may carry a different rate, and the guest's company has to separate it to claim the room credit.
- Charging 18% on spa services. Beauty and physical well-being services are 5% without credit since 22 September 2025.
- No GSTIN for a business guest. Without it the bill is B2C and the company cannot claim anything.
- Ignoring the deposit. GST on an advance is due when it is received; the final bill must adjust it, not charge it again.
Hotel bill vs restaurant bill vs travel agent bill
| Hotel bill | Restaurant bill | Travel agent bill | |
|---|---|---|---|
| Who issues it | Hotel, lodge, guest house, homestay | Restaurant, cafe, hotel restaurant | Agent or tour operator |
| Main SAC | 996311 (rooms) | 996331 | 9985 |
| Usual GST | 5% (rooms up to ₹7,500) or 18% | 5%, or 18% in a specified premises | 18% on the agent's fee; 5% on a tour package |
| Place of supply | Where the hotel is, always | Where the restaurant is | Usually the customer's location |
| Credit for a business buyer | Room yes (same state); food no | No, blocked | Yes on the fee |
| Format | Hotel bill format | Restaurant bill format | Travel bill format |
Key terms
- Folio
- The running account of a guest's charges during a stay, closed into the bill at check-out.
- Value of supply per unit per day
- The amount actually charged for one room for one night, used to decide between 5% and 18%.
- Specified premises
- A hotel that sold any room above ₹7,500 a day in the previous financial year, or declared itself one; its restaurants charge 18% with credit.
- Place of supply
- The state whose GST applies; for accommodation, the state where the property is.
- SAC 996311
- Services accounting code for room or unit accommodation in hotels and similar establishments.
- Receipt voucher
- The GST document a supplier issues when it receives an advance, showing the tax on it.
Questions people ask
What GST applies to hotel rooms?
From 22 September 2025, rooms with a value up to ₹7,500 per unit per day are taxed at 5% without input tax credit for the hotel, and rooms above ₹7,500 at 18% with credit. The 5% rate is mandatory. The test uses the value actually charged per night, including extra beds, not the published tariff.
What GST applies to food on a hotel bill?
5% without credit, unless the hotel is a specified premises, in which case 18% with credit. A hotel is a specified premises for a year if it sold any room above ₹7,500 a day in the previous financial year, or if it declared itself one. Food included in the room tariff takes the room's rate.
Can a business guest claim GST on a hotel bill?
On the room, yes in principle, if the bill carries the company's name and GSTIN and the stay was for business. In practice the credit works only for a GSTIN in the hotel's state, because the hotel charges CGST and SGST of its own state. GST on food is blocked credit under section 17(5).
Why does a hotel charge CGST and SGST to a guest from another state?
For accommodation, section 12(3) of the IGST Act makes the place of supply the location of the property. Every stay is therefore an intra-state supply in the hotel's state, whoever the guest is. A hotel never charges IGST for a room in India.
Is there GST on rooms below ₹1,000?
Yes, if the hotel is registered. The exemption for rooms below ₹1,000 a day was withdrawn from 18 July 2022, and such rooms are now taxed at 5%. A hotel below the registration threshold charges no GST at all.
Is GST charged on the advance deposit?
Yes. For services, GST is due when the advance is received. The hotel issues a receipt voucher with the tax, and the final bill deducts the deposit. If the booking is cancelled and the deposit refunded, the hotel issues a refund voucher.
What GST applies to cancellation and no-show charges?
The same rate as the room. CBIC Circular 178/10/2022-GST treats cancellation charges for hotel accommodation as consideration for the accommodation, so a retention on a ₹4,800 room is taxed at 5%.
Is breakfast taxed separately from the room?
Not when it is included in the tariff. Room with breakfast is a composite supply in which the room is the principal supply, so the whole tariff is taxed at the room's rate. Breakfast bought separately is restaurant service at the restaurant rate.
What is the SAC code for hotel rooms?
996311 for room or unit accommodation in hotels, inns, guest houses and similar places, within heading 9963. Restaurant service is 996331.
Can I get this hotel bill format in Word or PDF?
This page is an online editor, not a Word file: fill it in here and the totals and GST are worked out for you. You can download it as a PDF free, with a small LuckPanda footer. Signing in issues it as a numbered bill you can email; issuing, sending and clean PDFs without our branding need the Sales module.