 luckpanda
Quick answer
What is the proforma invoice format in India?
An Indian proforma invoice follows the GST tax invoice layout but is titled "Proforma invoice" and numbered in its own series. It shows the seller's and buyer's GSTIN, each item with HSN or SAC, quantity, rate, taxable value and the CGST and SGST or IGST expected, plus validity, the advance required, delivery terms and bank details. It creates no GST liability and gives the buyer no input tax credit.
- Top: "Proforma invoice", PI number, date, valid-until date.
- Middle: parties with GSTIN and state code, then the item table with HSN/SAC and GST.
- Foot: advance and balance terms, delivery, bank details, "not a tax invoice", signature.
- For the full rules (customs, letters of credit, other countries) see the proforma invoice guide.
Last reviewed:
On this page
- The proforma invoice format, block by block
- How to fill in this proforma invoice format
- Worked example: a 30% advance on a ₹5.29 lakh order
- Where Indian buyers need a proforma, and what they check
- Format variants: goods, services and exports
- GST rules that touch a proforma invoice
- Proforma invoice format in Excel or Word
- From proforma to tax invoice
- Proforma invoice vs quotation vs tax invoice vs delivery challan
- Mistakes to avoid
- Key terms
- Questions people ask
The proforma invoice format, block by block
GST law does not prescribe a format for proforma invoices: they are commercial documents. Indian buyers, banks and departments nevertheless expect them to look like the tax invoice that will follow, because they check one against the other. The safest layout is the GST invoice format with three changes: the title, a separate number series and the payment terms block.
Narmada Electrical Drives in Vadodara is supplying four motors with control panels to an agro-processing plant in Indore. The buyer's board approves capital purchases against a proforma, and the supplier wants 30% before it starts building the panels.
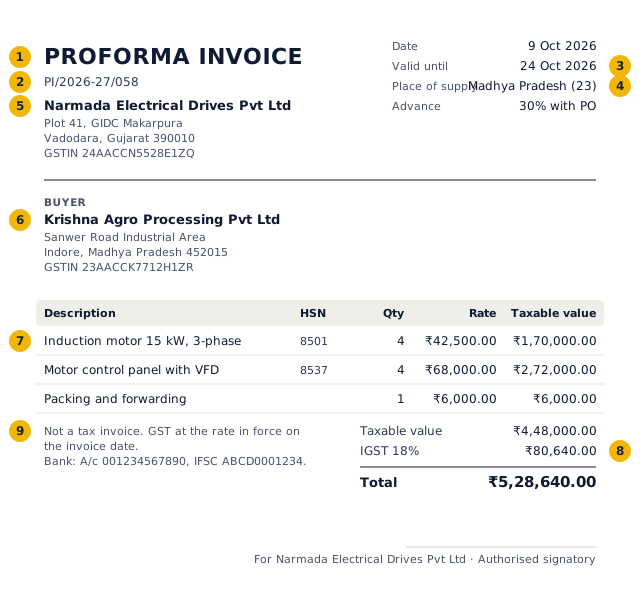
- "Proforma invoice", never "Tax invoice", so the buyer does not book it or claim credit.
- PI number from its own series, here with the financial year.
- Valid until: banks and boards reject stale proformas; 15 to 30 days is usual.
- Place of supply with state code: decides IGST or CGST plus SGST on the tax invoice.
- Seller GSTIN, legal name and address, exactly as on the tax invoice.
- Buyer GSTIN and address; banks match the name to the loan or remittance file.
- HSN or SAC per line, at the digits your turnover requires on the tax invoice.
- GST shown for information: nothing is payable on the proforma itself.
- Bank details for the advance and a "not a tax invoice" line.
| Block | What to put in it | Indian practice |
|---|---|---|
| Header | "Proforma invoice", PI number, date, valid-until date | Financial-year prefix (PI/2026-27/058) keeps numbers unique when the series restarts in April |
| Seller | Legal name, address, GSTIN, state and code, PAN, contact | Add your IEC on export proformas and your MSME (Udyam) number if buyers pay MSMEs to a deadline |
| Buyer | Name, billing and delivery address, GSTIN, state and code | Government buyers want the exact department name; loan proformas need the borrower's name as in the loan file |
| Items | Description, HSN or SAC, quantity, unit, rate, discount, taxable value | Model numbers, makes and specifications; lenders and auditors check them against the asset |
| GST | CGST and SGST, or IGST, at the expected rate | Write "for information; GST at the rate in force on the invoice date" |
| Totals | Taxable value, GST, total, amount in words | Amount in words is customary, not a GST requirement |
| Terms | Advance %, balance terms, delivery period, freight, insurance, warranty, validity | Name the advance in rupees as well as a percentage |
| Bank details | Account name, number, IFSC, branch; UPI for small amounts | The buyer's bank pays to exactly these details |
| Foot | "This is not a tax invoice", jurisdiction, signature and stamp | Banks and departments usually want it signed and stamped |
How to fill in this proforma invoice format
- Add your business with GSTINYour legal name, address and GSTIN as on your registration. The title already reads "Proforma invoice".
- Add the buyer and place of supplyEnter the buyer's name, address and GSTIN. The two state codes decide whether the GST shown is IGST or CGST plus SGST; change the place of supply if the goods go elsewhere.
- List items with HSN or SAC and GSTOne line per item with code, quantity, unit and rate. Set the GST rate you expect on the tax invoice: 5%, 18% or 40% after 22 September 2025.
- Write the advance, delivery and validityIn the terms: the advance in percent and rupees, when the balance is due, the delivery period, freight and the valid-until date. Put bank details and "Not a tax invoice" in the notes.
- Sign in to number and convert itCreating here is free. Signing in gives it the next PI number, lets you send it, and converts it into the tax invoice when the order is confirmed; downloading the PDF is free with a small LuckPanda footer, while issuing, sending and clean PDFs without our branding need the Sales module.
Worked example: a 30% advance on a ₹5.29 lakh order
Proforma PI/2026-27/058: motors and control panels, IGST 18%
| Item | HSN/SAC | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|---|
| Induction motor 15 kW, 3-phase | 8501 | 4 | ₹42,500.00 | ₹1,70,000.00 | ₹30,600.00 |
| Motor control panel with VFD | 8537 | 4 | ₹68,000.00 | ₹2,72,000.00 | ₹48,960.00 |
| Packing and forwarding | 1 | ₹6,000.00 | ₹6,000.00 | ₹1,080.00 | |
| Taxable value | ₹4,48,000.00 | ||||
| IGST 18% | ₹80,640.00 | ||||
| Total | ₹5,28,640.00 | ||||
The proforma asks for 30% of the total, ₹1,58,592.00, with the purchase order. Because these are goods, no GST is payable on the advance; Narmada simply issues a receipt for the money. At dispatch it issues the tax invoice for ₹5,28,640.00, reports it in GSTR-1, and shows the advance received and the balance of ₹3,70,048.00 due.
Where Indian buyers need a proforma, and what they check
| Use | Who asks for it | What they check on the proforma |
|---|---|---|
| Vehicle loan | The buyer's bank or NBFC, before disbursing to the dealer | Make, model, variant and colour; ex-showroom price with GST; registration, insurance and accessories shown separately; dealer's GSTIN and bank account |
| Machinery or equipment loan | Bank financing plant and machinery, including under MSME schemes | Supplier's GSTIN and standing, item specifications, price per unit, delivery period; often two or three competing proformas |
| Education loan | Lender disbursing fees directly to the institution | Institution's name, student's name, course, fee heads and the account to pay; many institutions issue a fee demand letter instead |
| Government purchase | Department sanctioning budget or releasing an advance | Exact department name, rates matching the approved quotation, validity; advances are usually paid against a bank guarantee |
| Import payment | The importer's bank remitting an advance abroad | Supplier's name and country, goods, amount and currency, payment terms; banks also accept a purchase order or contract |
| Export order | The foreign buyer, for its import licence or letter of credit | Currency, HS code, Incoterms, port of loading, shipment date, your IEC and bank details |
| Internal approval | The buyer's purchase committee or board | Total cost including GST, freight and installation; payment schedule |
For a loan, make the proforma out to the borrower, not the bank, unless the bank tells you otherwise, and keep the price on the tax invoice the same as the proforma: lenders compare the two before releasing the last instalment.
Format variants: goods, services and exports
- Goods, domestic. The layout above: HSN codes, quantities and units, freight and insurance terms, delivery period. No GST on the advance.
- Services. SAC codes, a description of the scope or milestones instead of quantities, and the payment schedule by milestone. Each advance received needs a receipt voucher with GST.
- Export. Price in the buyer's currency, HS code (8-digit ITC-HS for the shipping bill), Incoterms, port of loading and discharge, country of origin, your IEC and the bank's SWIFT code. GST is not shown as payable: say "Export, zero-rated" and let the tax invoice carry the rule 46 endorsement for supply under LUT or on payment of IGST. The export invoice format shows that invoice.
- Quotation-cum-proforma. Some traders send one document titled "Quotation / Proforma invoice". It works for small orders, but banks and departments prefer a proforma issued after the price is agreed, with the buyer's reference on it.
GST rules that touch a proforma invoice
- Does a proforma invoice create GST liability?
- No. GST is due at the time of supply, which a proforma does not mark. It is not a tax invoice under section 31 and is not reported in GSTR-1.
- Can the buyer claim input tax credit on it?
- No. Section 16 allows credit only on a tax invoice, debit note or other prescribed document. Buyers who book proformas as purchases have to reverse the credit later.
- Is GST payable on the advance?
- For goods, no: Notification 66/2017-Central Tax (15 November 2017) removed it for all taxpayers except those under the composition scheme. For services, yes: a receipt voucher (rule 50) and GST in the month of receipt, reported in GSTR-1 table 11A.
- Which GST rate goes on the proforma if rates change?
- The rate in force when the supply happens, not when the proforma was written. When GST was rationalised on 22 September 2025, proformas issued earlier at 12% or 28% became wrong for many goods that moved to 5% or 18%. Write "GST at the rate in force on the date of invoice" and update the proforma if the buyer needs an exact figure.
- Does the proforma number have to follow GST rules?
- No, but follow them anyway: up to 16 characters, letters, numbers, hyphen and slash, unique for the financial year. It keeps your systems consistent and avoids confusion with tax invoice numbers.
Proforma invoice format in Excel or Word
A spreadsheet works for a handful of proformas. If you build one, lay the item table out like this, and keep the GST type driven by the state codes rather than typed by hand.
| Column | Content | Formula or rule |
|---|---|---|
| A | S. no. | 1, 2, 3… |
| B | Description | Make, model, specification |
| C | HSN/SAC | Text, so leading zeros are kept |
| D | Qty | Number |
| E | Unit | NOS, KGS, MTR… |
| F | Rate | Price per unit before GST |
| G | Taxable value | =ROUND(D*F - discount, 2) |
| H | GST % | 5, 18 or 40 after 22 Sep 2025 |
| I | IGST | If seller and buyer state codes differ: =ROUND(G*H/100, 2) |
| J, K | CGST, SGST | If the state codes match: each =ROUND(G*H/200, 2) |
| L | Line total | =G+I+J+K |
What goes wrong in spreadsheets: proformas numbered in the invoice series, a copied file that keeps the last buyer's GSTIN, CGST and SGST on an inter-state sale, rounding done on the total instead of each line, and no record of which proformas were converted. Word templates have the same problems without the arithmetic. The editor above works the GST out from the two GSTINs and keeps the PI series separate once you sign in.
From proforma to tax invoice
- Issue the tax invoice at supplyFor goods, on or before removal or delivery; for services, within 30 days of supply (rule 47). Use the next number in your tax invoice series.
- Carry the details acrossSame parties, items, HSN and rates as the proforma, unless the order changed. Quote the proforma number and the buyer's purchase order.
- Show the advanceTotal, less advance received, balance due. For services, adjust the GST already paid on the advance.
- Report and closeReport the tax invoice in GSTR-1. Mark the proforma converted so it is not invoiced again.
Proforma invoice vs quotation vs tax invoice vs delivery challan
| Quotation | Proforma invoice | Tax invoice | Delivery challan | |
|---|---|---|---|---|
| Purpose | Offer a price | State agreed terms; ask for an advance | Bill the supply and charge GST | Move goods without a sale (job work, approval, branch transfer) |
| GST law | None | None | Section 31, rule 46 | Rule 55 |
| GST payable | No | No (services advance: yes, via receipt voucher) | Yes | No |
| Buyer's ITC | No | No | Yes | No |
| In GSTR-1 | No | No | Yes | No (summary of documents only) |
| Numbering | Quote series | PI series | Consecutive, unique per financial year | Own series |
A proforma is sometimes called a "kachcha bill". That is misleading: a kachcha bill usually means an informal bill kept outside the books. A proforma is a formal offer on your letterhead with your GSTIN, and it should be filed with the order.
Mistakes to avoid
- Titling it "Tax invoice" or "Invoice". The buyer may book it and claim credit that has to be reversed.
- Using the tax invoice series. Unconverted proformas leave gaps in the series you report in GSTR-1.
- Charging GST on a goods advance. It is not due; a receipt is enough.
- Not charging GST on a services advance. It is due in the month of receipt, with a receipt voucher.
- No validity date. A loan or board approval on a stale price causes trouble when the tax invoice differs.
- Different prices on the tax invoice. Lenders and auditors compare the two; issue a revised proforma first.
- Leaving out bank details. The advance is the point of most proformas.
Key terms
- Proforma invoice
- A seller's statement of the terms of an agreed sale, issued before supply; not a GST tax invoice.
- Receipt voucher
- The document issued when an advance for services is received; GST is paid on it (rule 50).
- Place of supply
- The state where a supply is taxed; compared with the supplier's state it decides IGST or CGST plus SGST.
- HSN / SAC
- Codes that classify goods (HSN) and services (SAC) on GST documents.
- IEC
- Importer-Exporter Code issued by DGFT; required for imports and exports and shown on export proformas.
Questions people ask
Is GST payable on a proforma invoice?
No. GST becomes payable when the tax invoice is issued at supply or, for services, when an advance is received. A proforma invoice is only an offer.
Is GST payable on an advance received against a proforma?
For goods, no: GST on advances for goods was removed from 15 November 2017 for all taxpayers except composition dealers. For services, yes: issue a receipt voucher and pay GST on the advance in the month you receive it.
Can the buyer claim input tax credit on a proforma invoice?
No. Credit needs a tax invoice, debit note or another prescribed document. The buyer claims credit on the tax invoice that follows.
Why do banks ask for a proforma invoice?
Because they pay the seller directly or remit money abroad, and need the seller's own statement of price, terms and bank account: for vehicle, machinery and education loans, import advances and letters of credit.
Should a proforma invoice show GST?
Yes, for information, so the buyer knows the full cost: CGST and SGST for a buyer in your state, IGST for another state. Say that GST will be charged at the rate in force on the invoice date.
Is there a prescribed proforma invoice format under GST?
No. GST rules prescribe the tax invoice (rule 46), not the proforma. Following the tax invoice layout is still the best practice, because buyers and banks compare the two.
Can I make a proforma invoice in Excel?
Yes. Keep a separate PI series, calculate GST per line, choose IGST or CGST plus SGST from the state codes, and record which proformas became invoices. The column layout above shows the formulas.
What is the proforma invoice format for a vehicle loan?
The dealer's proforma in the buyer's name with make, model, variant, ex-showroom price including GST, and registration, insurance and accessories as separate lines, plus the dealer's GSTIN and bank account. The lender pays the dealer against it.
Do I need to sign a proforma invoice?
GST law does not require it, but banks and government departments usually do. Sign and stamp it, or sign it digitally.