 luckpanda
Quick answer
Tax invoice format: what it is
A tax invoice is the document a GST-registered seller issues to charge for goods or services; it fixes the taxable value and the CGST, SGST or IGST, and it is what the buyer claims input tax credit on. Who issues a GST tax invoice, when, and in how many copies.
Last reviewed:
On this page
- Example: a filled tax invoice format
- How to fill in the tax invoice format
- Tax invoice, bill of supply or voucher?
- Copies and records
- Worked example: inter-state services
- What to put on an invoice, field by field
- India GST rules for an invoice
- Mistakes to avoid
- Invoice vs other sales documents
- Questions people ask
Example: a filled tax invoice format
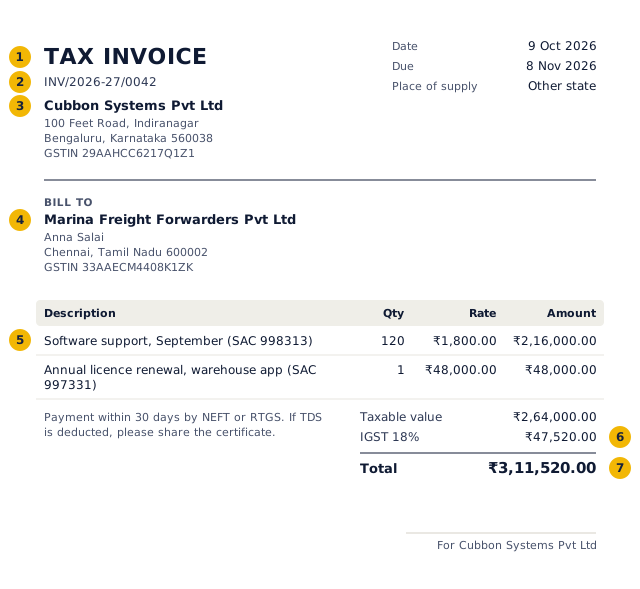
- The title says what the document is: an invoice.
- A unique number from a continuous series, allocated when you issue it.
- Your name, address and GSTIN.
- Who it is for.
- Each line: description, HSN/SAC, quantity, rate and taxable value.
- GST split by component: CGST and SGST in the same state, IGST across states.
- The total in the document's currency and format.
Worked example: the numbers behind the invoice above
| Item | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|
| Software support, September (SAC 998313) | 120 | ₹1,800.00 | ₹2,16,000.00 | ₹38,880.00 |
| Annual licence renewal, warehouse app (SAC 997331) | 1 | ₹48,000.00 | ₹48,000.00 | ₹8,640.00 |
| Taxable value | ₹2,64,000.00 | |||
| IGST 18% | ₹47,520.00 | |||
| Total | ₹3,11,520.00 | |||
GST is worked out per line and split into CGST and SGST (same state) or IGST (other state) from the two GSTINs.
How to fill in the tax invoice format
- Title the document "Tax invoice" and enter your GSTIN.
- Issue it on time: at removal of goods, or within 30 days for services.
- Add the buyer, items, HSN or SAC and GST rates.
- Save it, then sign in to issue it in sequence and report it in GSTR-1.
Tax invoice, bill of supply or voucher?
| Document | Issued by | When |
|---|---|---|
| Tax invoice | Registered supplier, taxable supply | At supply, within the time limits |
| Bill of supply | Composition taxpayer or exempt supplier | At supply |
| Receipt voucher | Supplier receiving an advance for services | On receiving the advance |
| Refund voucher | Supplier refunding an advance when no supply follows | On refund |
| Credit or debit note | Supplier correcting an invoice | After the invoice |
| Self-invoice | Recipient paying reverse charge on a purchase from an unregistered supplier | On receiving the supply |
Copies and records
Goods need three copies: the original for the recipient, the duplicate for the transporter and the triplicate for the supplier. Services need two. Where an e-invoice has been generated, the transporter need not carry a paper duplicate. Keep tax invoices for 72 months from the due date of the annual return for the year.
Worked example: inter-state services
A Bengaluru IT company bills a Chennai client for 120 hours of software support at ₹1,800 an hour and a ₹48,000 annual licence renewal. Taxable value ₹2,64,000. The supply crosses states, so IGST at 18% is ₹47,520 and the total ₹3,11,520. The invoice is issued within 30 days of the month's service.
What to put on an invoice, field by field
| Field | What to enter |
|---|---|
| Document title | Say exactly what it is: "Tax invoice". The title tells the buyer and the tax authority how to treat it. |
| Number and date | A unique number in a continuous series (at most 16 characters, unique for the financial year) and the issue date. LuckPanda allocates the number when you issue. |
| Your business | Name, address and GSTIN (state code is the first two digits) |
| Customer | Name, address and GSTIN if registered; for unregistered buyers, name, address and state |
| Lines | Description, quantity, unit and rate, with the HSN code for goods or SAC for services. Each line carries its own tax rate. |
| Tax | GST rate per line. Same state: CGST and SGST, half each. Another state or export: IGST. |
| Totals | Taxable value, tax by component and the total, in the document currency. Amounts in words are customary in India. |
| Terms | Due date, bank or payment details and late-payment terms. |
India GST rules for an invoice
- Contents are set by rule 46 of the CGST Rules: supplier name, address and GSTIN; a consecutive serial number of up to 16 characters, unique for the financial year; date; recipient details and GSTIN if registered; HSN or SAC; description, quantity, taxable value; rate and amount of CGST, SGST/UTGST or IGST; place of supply for inter-state supplies; a reverse-charge statement where it applies; and a signature.
- HSN digits: businesses with aggregate turnover up to ₹5 crore show 4 digits on B2B invoices; above ₹5 crore, 6 digits on every invoice.
- Timing: for goods, on or before removal or delivery; for services, within 30 days of supply.
- E-invoicing (an IRN from the Invoice Registration Portal) applies to B2B invoices of businesses whose aggregate turnover crossed ₹5 crore in any year since 2017-18.
- Unregistered or composition sellers do not issue tax invoices: they issue a bill of supply and charge no GST.
Mistakes to avoid
- Editing or deleting an issued invoice instead of issuing a credit note.
- Gaps or duplicates in the number series.
- Charging the wrong tax type (for India: IGST on an intra-state sale, or CGST and SGST across states).
- Leaving out the due date and payment details, which is the commonest reason invoices are paid late.
- Rounding each line's tax differently from the total; LuckPanda computes tax per line and keeps the components adding up.
Invoice vs other sales documents
| Document | When | Asks for payment | Tax document | In the books |
|---|---|---|---|---|
| Quotation / estimate | Before the order | No | No | No |
| Proforma invoice | After the order, before supply | Advance only | No | No |
| Invoice / tax invoice | On supply | Yes | Yes | Yes: sale and receivable |
| Receipt | When paid | No, confirms payment | No (receipt voucher for advances in India) | Yes: payment |
| Credit note | After an invoice, to reduce it | No, reduces what is owed | Yes | Yes: reverses part of the sale |
Questions people ask
Who must issue a tax invoice?
Every GST-registered person making a taxable supply, except composition taxpayers and suppliers of only exempt goods or services, who issue a bill of supply instead.
When must a tax invoice be issued?
For goods, before or at the time of removal for delivery, or of making them available where they do not move. For services, within 30 days of supply, or 45 days for banks, insurers and NBFCs. For continuous supplies, by each payment or statement date.
Is a tax invoice the same as an e-invoice?
An e-invoice is a tax invoice registered on the Invoice Registration Portal, which returns an IRN and a signed QR code. It is compulsory for B2B invoices of businesses with aggregate turnover above ₹5 crore.
What is a revised tax invoice?
An invoice issued, within one month of receiving the registration certificate, for supplies made between the effective date of registration and the date the certificate was issued. It replaces invoices issued without GST in that period.