 luckpanda
Quick answer
Labour bill format: what it is
A tax invoice is the document a GST-registered seller issues to charge for goods or services; it fixes the taxable value and the CGST, SGST or IGST, and it is what the buyer claims input tax credit on. Labour contractor bill: man-days by skill, overtime, supervision, GST.
Last reviewed:
On this page
Example: a filled invoice
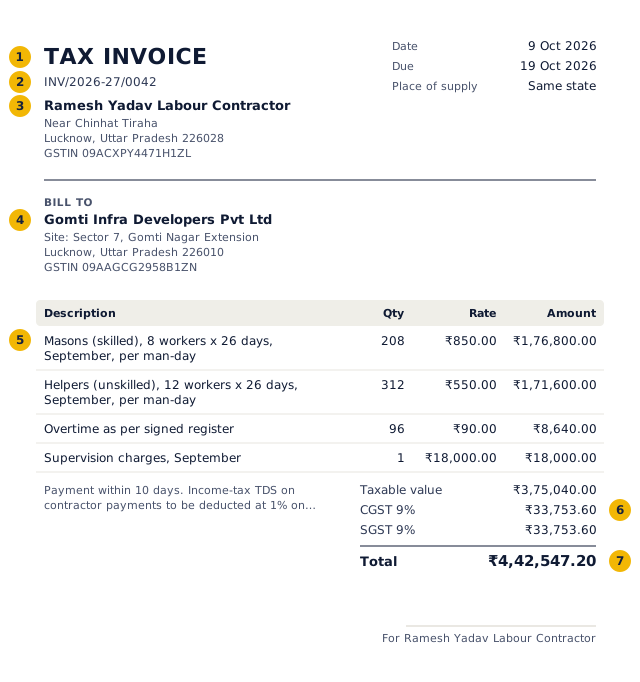
- The title says what the document is: an invoice.
- A unique number from a continuous series, allocated when you issue it.
- Your name, address and GSTIN.
- Who it is for.
- Each line: description, HSN/SAC, quantity, rate and taxable value.
- GST split by component: CGST and SGST in the same state, IGST across states.
- The total in the document's currency and format.
Worked example: the numbers behind the invoice above
| Item | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|
| Masons (skilled), 8 workers x 26 days, September, per man-day | 208 | ₹850.00 | ₹1,76,800.00 | ₹31,824.00 |
| Helpers (unskilled), 12 workers x 26 days, September, per man-day | 312 | ₹550.00 | ₹1,71,600.00 | ₹30,888.00 |
| Overtime as per signed register | 96 | ₹90.00 | ₹8,640.00 | ₹1,555.20 |
| Supervision charges, September | 1 | ₹18,000.00 | ₹18,000.00 | ₹3,240.00 |
| Taxable value | ₹3,75,040.00 | |||
| CGST 9% | ₹33,753.60 | |||
| SGST 9% | ₹33,753.60 | |||
| Total | ₹4,42,547.20 | |||
GST is worked out per line and split into CGST and SGST (same state) or IGST (other state) from the two GSTINs.
How to fill in the labour bill format
- Add your name or firm, address, GSTIN, PAN and labour licence number if you hold one.
- Add the principal employer and the site.
- Bill man-days by skill category, then overtime and supervision, from the signed muster roll.
- Apply GST, note the TDS the client will deduct, then save.
Labour bill format
- Contractor name, address, GSTIN, PAN and labour licence number
- Bill number and date; work order number
- Principal employer and site address
- Billing period
- Man-days by category: skilled, semi-skilled and unskilled, with the rate for each
- Overtime hours and rate
- Supervision or service charges
- GST rate and amount
- A statement that wages for the period have been paid, with PF and ESI challan references where they apply
Worked example
| Category | Workers x days | Quantity | Rate (₹) | Amount (₹) |
|---|---|---|---|---|
| Mason (skilled) | 8 x 26 | 208 man-days | 850 | 1,76,800 |
| Helper (unskilled) | 12 x 26 | 312 man-days | 550 | 1,71,600 |
| Overtime | 96 hours | 90 | 8,640 | |
| Supervision charges | 1 month | 18,000 | 18,000 | |
| Taxable value | 3,75,040 | |||
| GST at 18% | 67,507.20 | |||
| Bill total | 4,42,547.20 |
What to put on an invoice, field by field
| Field | What to enter |
|---|---|
| Document title | Say exactly what it is: "Tax invoice". The title tells the buyer and the tax authority how to treat it. |
| Number and date | A unique number in a continuous series (at most 16 characters, unique for the financial year) and the issue date. LuckPanda allocates the number when you issue. |
| Your business | Name, address and GSTIN (state code is the first two digits) |
| Customer | Name, address and GSTIN if registered; for unregistered buyers, name, address and state |
| Lines | Description, quantity, unit and rate, with the HSN code for goods or SAC for services. Each line carries its own tax rate. |
| Tax | GST rate per line. Same state: CGST and SGST, half each. Another state or export: IGST. |
| Totals | Taxable value, tax by component and the total, in the document currency. Amounts in words are customary in India. |
| Terms | Due date, bank or payment details and late-payment terms. |
India GST rules for an invoice
- Contents are set by rule 46 of the CGST Rules: supplier name, address and GSTIN; a consecutive serial number of up to 16 characters, unique for the financial year; date; recipient details and GSTIN if registered; HSN or SAC; description, quantity, taxable value; rate and amount of CGST, SGST/UTGST or IGST; place of supply for inter-state supplies; a reverse-charge statement where it applies; and a signature.
- HSN digits: businesses with aggregate turnover up to ₹5 crore show 4 digits on B2B invoices; above ₹5 crore, 6 digits on every invoice.
- Timing: for goods, on or before removal or delivery; for services, within 30 days of supply.
- E-invoicing (an IRN from the Invoice Registration Portal) applies to B2B invoices of businesses whose aggregate turnover crossed ₹5 crore in any year since 2017-18.
- Unregistered or composition sellers do not issue tax invoices: they issue a bill of supply and charge no GST.
Mistakes to avoid
- Editing or deleting an issued invoice instead of issuing a credit note.
- Gaps or duplicates in the number series.
- Charging the wrong tax type (for India: IGST on an intra-state sale, or CGST and SGST across states).
- Leaving out the due date and payment details, which is the commonest reason invoices are paid late.
- Rounding each line's tax differently from the total; LuckPanda computes tax per line and keeps the components adding up.
Invoice vs other sales documents
| Document | When | Asks for payment | Tax document | In the books |
|---|---|---|---|---|
| Quotation / estimate | Before the order | No | No | No |
| Proforma invoice | After the order, before supply | Advance only | No | No |
| Invoice / tax invoice | On supply | Yes | Yes | Yes: sale and receivable |
| Receipt | When paid | No, confirms payment | No (receipt voucher for advances in India) | Yes: payment |
| Credit note | After an invoice, to reduce it | No, reduces what is owed | Yes | Yes: reverses part of the sale |
Questions people ask
What is a man-day?
One worker for one day, usually 8 hours. Ten helpers for 26 days is 260 man-days. Billing in man-days lets the client check the bill against the attendance register.
Is GST charged on a labour bill?
A registered labour or manpower supply contractor generally charges 18%. Pure labour contracts for building a single residential unit that is not part of a residential complex are exempt. Check the current notifications for your type of work.
What TDS does the client deduct?
Income-tax TDS on contractor payments (section 194C of the 1961 Act; section 393 of the Income-tax Act, 2025 from 1 April 2026): 1% if the contractor is an individual or HUF and 2% otherwise, on the bill value excluding GST shown separately, once payments cross the single-payment or annual thresholds.
Can labour rates be below minimum wages?
No. Workers must be paid at least the minimum wage notified for their skill category in the state, and the principal employer can be held liable if the contractor does not pay. The rate you bill has to cover wages, statutory contributions and your margin.