 luckpanda
Quick answer
Bill of supply format: what it is
A bill of supply is the GST document a registered seller issues instead of a tax invoice when it may not charge GST: for exempt supplies, or for every supply if it is under the composition scheme (rule 49 of the CGST Rules). For composition dealers and exempt supplies, no GST.
Last reviewed:
On this page
Example: a filled bill of supply format
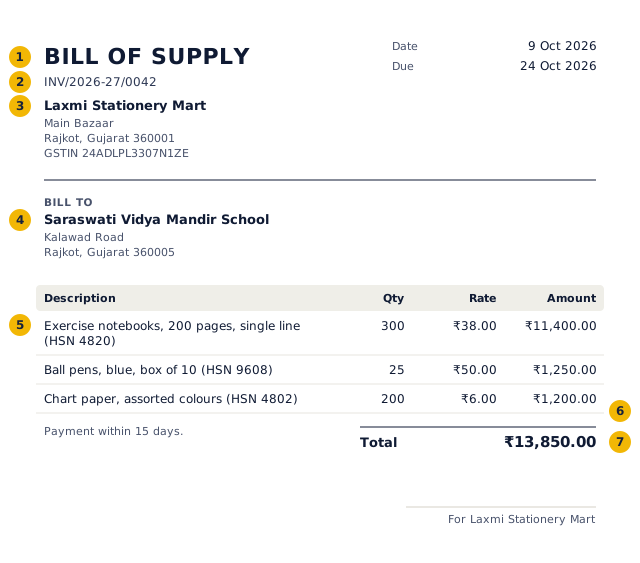
- The title says what the document is: a bill of supply.
- A unique number from a continuous series, allocated when you issue it.
- Your name, address and GSTIN.
- Who it is for.
- Each line: description, HSN/SAC, quantity, rate and taxable value.
- GST split by component: CGST and SGST in the same state, IGST across states.
- The total in the document's currency and format.
Worked example: the numbers behind the bill of supply above
| Item | Qty | Rate | Taxable value | Tax |
|---|---|---|---|---|
| Exercise notebooks, 200 pages, single line (HSN 4820) | 300 | ₹38.00 | ₹11,400.00 | ₹0.00 |
| Ball pens, blue, box of 10 (HSN 9608) | 25 | ₹50.00 | ₹1,250.00 | ₹0.00 |
| Chart paper, assorted colours (HSN 4802) | 200 | ₹6.00 | ₹1,200.00 | ₹0.00 |
| Subtotal | ₹13,850.00 | ₹0.00 | ||
| Total | ₹13,850.00 | |||
No tax is charged on these lines, so the total equals the value of the supply.
How to fill in the bill of supply format
- Title it "Bill of supply" and add your GSTIN.
- If you are under composition, include the declaration; Rule 49 places it at the top.
- List items with HSN or SAC, quantity and value, with no GST.
- Save it; sign in to number bills in their own consecutive series.
Bill of supply format (Rule 49)
- Title "Bill of supply"
- Supplier name, address and GSTIN
- Consecutive serial number, up to 16 characters, unique for the financial year
- Date of issue
- Recipient name, address and GSTIN or UIN if registered
- HSN or SAC
- Description of the goods or services
- Value of the supply after discounts
- Signature or digital signature
- For composition taxpayers: "composition taxable person, not eligible to collect tax on supplies"
The composition scheme in brief
The turnover limit is ₹1.5 crore for goods (₹75 lakh in some special category states) and ₹50 lakh for service providers. Composition taxpayers cannot claim input tax credit or make inter-state supplies of goods.
| Taxpayer | Tax on turnover | Can charge GST to buyers? |
|---|---|---|
| Manufacturers and traders | 1% (0.5% CGST and 0.5% SGST) | No |
| Restaurants not serving alcohol | 5% | No |
| Service providers under section 10(2A) | 6% | No |
India GST rules for a bill of supply
- Rule 49 sets the contents: the title "Bill of supply", supplier name, address and GSTIN, a consecutive serial number of up to 16 characters, date, recipient details, HSN or SAC, description, value and signature.
- Composition taxpayers print "composition taxable person, not eligible to collect tax on supplies" at the top.
- No GST is shown or charged, and the buyer gets no input tax credit.
- A registered person supplying both taxable and exempt items to an unregistered buyer may issue one invoice-cum-bill of supply.
Mistakes to avoid
- Editing or deleting an issued invoice instead of issuing a credit note.
- Gaps or duplicates in the number series.
- Charging the wrong tax type (for India: IGST on an intra-state sale, or CGST and SGST across states).
- Leaving out the due date and payment details, which is the commonest reason invoices are paid late.
- Rounding each line's tax differently from the total; LuckPanda computes tax per line and keeps the components adding up.
Bill of supply vs other sales documents
| Document | When | Asks for payment | Tax document | In the books |
|---|---|---|---|---|
| Quotation / estimate | Before the order | No | No | No |
| Proforma invoice | After the order, before supply | Advance only | No | No |
| Invoice / tax invoice | On supply | Yes | Yes | Yes: sale and receivable |
| Receipt | When paid | No, confirms payment | No (receipt voucher for advances in India) | Yes: payment |
| Credit note | After an invoice, to reduce it | No, reduces what is owed | Yes | Yes: reverses part of the sale |
Questions people ask
Who issues a bill of supply?
A registered person supplying exempt goods or services, and a composition taxpayer for all of its supplies.
What declaration must a composition dealer show?
The words "composition taxable person, not eligible to collect tax on supplies" at the top of the bill of supply. Composition taxpayers must also display that they are under composition at their place of business.
Can one document be both a tax invoice and a bill of supply?
Yes. A registered person supplying both taxable and exempt items to an unregistered buyer may issue a single invoice-cum-bill of supply.
Is a bill of supply needed for small amounts?
Not for a supply under ₹200 to an unregistered buyer who does not ask for one.