 luckpanda
Quick answer
VAT invoice template: what it is
A VAT invoice is the invoice a VAT-registered business must issue to another business: it shows the VAT number, the tax point, the VAT rate per item and the VAT charged, so the customer can reclaim it. Every field HMRC requires, VAT rate on each line.
Last reviewed:
On this page
Example: a filled VAT invoice
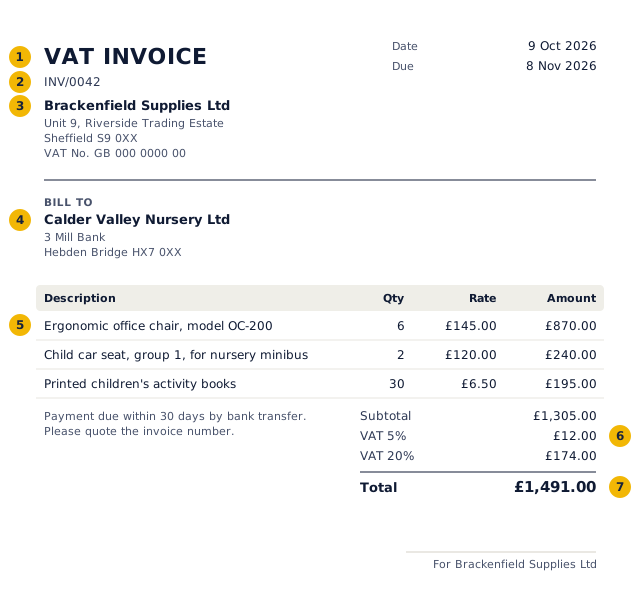
- The title says what the document is: a VAT invoice.
- A unique number from a continuous series, allocated when you issue it.
- Your business name and address, and tax number if registered.
- Who it is for.
- Each line: description, quantity, rate and amount.
- Tax by rate.
- The total in the document's currency and format.
Worked example: the numbers behind the VAT invoice above
| Item | Qty | Rate | Amount | Tax |
|---|---|---|---|---|
| Ergonomic office chair, model OC-200 | 6 | £145.00 | £870.00 | £174.00 |
| Child car seat, group 1, for nursery minibus | 2 | £120.00 | £240.00 | £12.00 |
| Printed children's activity books | 30 | £6.50 | £195.00 | £0.00 |
| Subtotal | £1,305.00 | |||
| VAT 5% | £12.00 | |||
| VAT 20% | £174.00 | |||
| Total | £1,491.00 | |||
Tax is worked out per line on the amount after any discount.
How to fill in the vat invoice
- Enter your business name, address and VAT registration number.
- Add the customer's name and address.
- Set the VAT rate on each line: 20%, 5% or 0%.
- Note the time of supply if it differs from the invoice date, then save.
Full VAT invoice requirements
- A unique, sequential invoice number
- Your business name and address
- Your VAT registration number
- The invoice date
- The time of supply, if different from the invoice date
- The customer's name or trading name and address
- A description that identifies the goods or services
- For each item: quantity, unit price excluding VAT, VAT rate and amount excluding VAT
- Any discount offered
- Total excluding VAT, total VAT and total including VAT
UK VAT rates
Zero-rated and exempt are not the same: zero-rated sales are taxable at 0% and count towards the registration threshold; exempt sales do not. If you invoice in another currency, the VAT must still be shown in sterling.
| Rate | Applies to (examples) |
|---|---|
| Standard 20% | Most goods and services |
| Reduced 5% | Domestic fuel and power, children's car seats, some energy-saving installations |
| Zero 0% | Most food, children's clothes, books and newspapers, exports of goods |
| Exempt | Insurance, most financial services, and education and health services from qualifying bodies |
UK VAT rules for a VAT invoice
- If you are VAT-registered, a full VAT invoice shows a unique sequential number, date, time of supply if different, your name, address and VAT number, the customer's name and address, a description, quantity and price, the VAT rate per item, the total without VAT and the VAT charged in sterling (HMRC VAT Notice 700, section 16).
- Retailers may issue a simplified invoice for supplies of £250 or less including VAT.
- Issue the VAT invoice within 30 days of the tax point.
- Limited companies must show the company name, registration number and registered office address on invoices.
- Not VAT-registered? Do not show VAT or a VAT number.
Mistakes to avoid
- Editing or deleting an issued invoice instead of issuing a credit note.
- Gaps or duplicates in the number series.
- Charging the wrong tax type (for India: IGST on an intra-state sale, or CGST and SGST across states).
- Leaving out the due date and payment details, which is the commonest reason invoices are paid late.
- Rounding each line's tax differently from the total; LuckPanda computes tax per line and keeps the components adding up.
VAT invoice vs other sales documents
| Document | When | Asks for payment | Tax document | In the books |
|---|---|---|---|---|
| Quotation / estimate | Before the order | No | No | No |
| Proforma invoice | After the order, before supply | Advance only | No | No |
| Invoice / tax invoice | On supply | Yes | Yes | Yes: sale and receivable |
| Receipt | When paid | No, confirms payment | No (receipt voucher for advances in India) | Yes: payment |
| Credit note | After an invoice, to reduce it | No, reduces what is owed | Yes | Yes: reverses part of the sale |
Questions people ask
When can I use a simplified VAT invoice?
For retail supplies of £250 or less including VAT. It needs fewer details: your name, address and VAT number, the time of supply, a description, the VAT rate for each item and the total including VAT.
What is the time of supply?
The tax point: normally the date goods are delivered or services completed. If you invoice within 14 days afterwards, the invoice date becomes the tax point. An advance payment creates its own tax point.
How long do I have to issue a VAT invoice?
Within 30 days of the time of supply, or of receiving payment if you were paid in advance.
What about the reverse charge?
Some supplies, such as construction services under the domestic reverse charge, are invoiced without VAT, with a note that the customer accounts for it. Show the amount of VAT due under the reverse charge.